Tag: investing strategy

  • Asset Allocation Strategy: Build a Portfolio That Lasts

    Asset Allocation Strategy: Build a Portfolio That Lasts

    What Is Asset Allocation and Why Does It Define Your Financial Future?

    According to a landmark study by Brinson, Hood, and Beebower — widely cited by Vanguard and Morningstar — asset allocation explains more than 90% of the variation in a portfolio’s long-term returns. Yet most investors spend the majority of their time trying to pick individual stocks, chasing the next hot fund, or timing the market.

    That’s the wrong game to play.

    Asset allocation is the strategy of dividing your investment portfolio among different asset categories — primarily stocks, bonds, and cash — in proportions that match your financial goals, risk tolerance, and time horizon. It’s not glamorous. It won’t go viral on social media. But it’s the single most powerful lever you control as an investor.

    In this guide, you’ll learn exactly how asset allocation works, how to build a strategy that fits your life, what common mistakes cost investors thousands of dollars, and how to adjust your mix as you age. Whether you’re 35 and just starting to build wealth or 58 and approaching retirement, this framework applies to you.

    How Asset Allocation Works: The Core Mechanics

    At its most basic level, asset allocation is about not putting all your eggs in one basket — but with a strategic rationale behind the basket choices, not just random diversification.

    The three main asset classes behave differently under various market conditions:

    • Stocks (equities): Higher long-term return potential, higher short-term volatility. The S&P 500 has delivered an average annual return of roughly 10% before inflation over the past century, according to data from Morningstar — but with years like 2008 (-37%) mixed in.
    • Bonds (fixed income): Lower return potential but more stability. Bonds tend to cushion portfolios when stocks fall. U.S. Treasury bonds are backed by the federal government and carry minimal default risk.
    • Cash and equivalents: Money market funds, CDs, and Treasury bills. Very low risk, very low return — but essential for liquidity and capital preservation.

    Beyond these three, many portfolios also include real estate investment trusts (REITs), international stocks, and commodities as additional diversification layers.

    The key insight: because these asset classes don’t move in perfect lockstep, combining them in the right proportions can reduce your overall portfolio risk without proportionally reducing your expected return. That’s the mathematical magic of diversification, formalized by Nobel laureate Harry Markowitz in his Modern Portfolio Theory.

    The Federal Reserve’s 2025 Survey of Consumer Finances found that households with diversified investment portfolios accumulated significantly more wealth over 20-year periods than those concentrated in a single asset class — reinforcing what the academic research has shown for decades.

    Key Benefits of a Disciplined Asset Allocation Strategy

    Understanding why asset allocation works in practice — not just in theory — helps you stick with it when markets get turbulent.

    1. It Manages Risk Without Eliminating Growth

    A portfolio of 100% stocks maximizes long-term growth potential but can drop 40-50% in a severe bear market. For a 55-year-old with $600,000 saved, that’s a $240,000-$300,000 paper loss — terrifying enough to cause panic selling at exactly the wrong time. A 60/40 portfolio (60% stocks, 40% bonds) historically softened those drawdowns to roughly 20-25% while still generating solid long-term gains.

    2. It Forces Disciplined Rebalancing

    When you have a target allocation, market movements will drift your portfolio away from it over time. Rebalancing — selling what’s grown and buying what’s lagged — enforces the discipline of "buy low, sell high" systematically. According to Vanguard research, disciplined rebalancing can add roughly 0.35% in annual returns over time compared to an unmanaged portfolio.

    3. It Aligns Your Portfolio With Your Real Life

    A 32-year-old software engineer saving for retirement 30 years away has a completely different risk profile than a 61-year-old planning to retire in four years. Asset allocation gives you a framework to match your investment risk to your actual life circumstances — not just generic advice.

    4. It Reduces Emotional Decision-Making

    When you have a written asset allocation policy, market volatility becomes a trigger for systematic action (rebalancing) rather than panic. This is one of the most underrated benefits — the behavioral finance research from Dalbar consistently shows that the average investor significantly underperforms the market they’re invested in because of emotional timing decisions.

    How to Build Your Asset Allocation Strategy: Step-by-Step

    Building your allocation isn’t a one-size-fits-all exercise. Here’s how to approach it systematically:

    Step 1: Define Your Time Horizon

    How many years until you need the money? For retirement accounts, this is usually the distance to age 65-70. Money you’ll need in under 5 years should be in conservative allocations. Money you won’t touch for 20+ years can tolerate much more stock exposure.

    Step 2: Assess Your Risk Tolerance — Honestly

    Risk tolerance has two components: your financial ability to absorb losses (based on income, savings, and time horizon) and your emotional ability to sleep at night during a bear market. Ask yourself: "If my portfolio dropped 30% in 12 months, would I stay the course or sell?" Be brutally honest.

    Step 3: Choose a Starting Allocation Model

    These are widely used starting frameworks — not rigid prescriptions:

    • Aggressive (80-100% stocks): Best for investors 35 and under with 25+ years to retirement and high risk tolerance.
    • Moderate-Aggressive (70/30): Suitable for investors in their 40s with strong income and 20+ year horizons.
    • Moderate (60/40): The classic balanced portfolio — appropriate for many investors in their 50s approaching retirement.
    • Conservative (40/60 or 30/70): For investors within 5-10 years of retirement or those with lower risk tolerance at any age.

    Step 4: Diversify Within Each Asset Class

    Don’t just hold "stocks" — diversify within stocks by holding U.S. large-cap, U.S. small-cap, international developed markets, and emerging markets. Within bonds, consider a mix of short-term and intermediate-term Treasuries, investment-grade corporate bonds, and possibly TIPS (Treasury Inflation-Protected Securities) to hedge inflation.

    Step 5: Implement With Low-Cost Index Funds or ETFs

    For most investors, low-cost index funds and ETFs are the most efficient way to implement an asset allocation strategy. According to the ICI (Investment Company Institute), the average expense ratio for index funds has fallen to around 0.05-0.20%, compared to 0.60-1.00%+ for actively managed funds. Over 30 years, that fee difference can represent hundreds of thousands of dollars in your pocket.

    For context on ETFs as a vehicle for this strategy, you may find it helpful to review Dollar-Cost Averaging: The Smart Way to Invest Consistently, which pairs naturally with an asset allocation plan.

    Step 6: Schedule Annual Rebalancing

    Set a calendar reminder once per year (or when any asset class drifts more than 5 percentage points from its target) to rebalance. Many 401(k) platforms offer automatic rebalancing — use it.

    Costs, Fees, and Risks You Need to Understand

    No investment strategy is free of costs or risks. Here’s what to watch for:

    Expense Ratios and Fund Fees

    Every fund charges an annual expense ratio. Even a 1% fee seems small but compounds dramatically — on a $500,000 portfolio, a 1% annual fee costs you $5,000 per year and potentially $150,000+ over 20 years compared to a 0.05% index fund. Always check the expense ratio before investing in any fund.

    Tax Drag from Rebalancing in Taxable Accounts

    Rebalancing in a taxable brokerage account can trigger capital gains taxes. The IRS taxes short-term capital gains (assets held under one year) as ordinary income — potentially up to 37% depending on your tax bracket. Long-term capital gains rates are more favorable (0%, 15%, or 20%). Strategy: prioritize rebalancing inside tax-advantaged accounts like your 401(k) or IRA first.

    Sequence-of-Returns Risk

    This is especially critical for investors near retirement. If the market crashes in the first few years of your retirement and you’re withdrawing funds, the combination of market losses and withdrawals can permanently impair your portfolio — even if markets eventually recover. A more conservative allocation as you approach retirement helps manage this risk.

    Inflation Risk in Conservative Portfolios

    Holding too much in bonds or cash carries its own risk: inflation erosion. With the CPI averaging around 2-3% historically (though higher in recent years), a portfolio yielding less than inflation loses purchasing power over time. This is why most financial planners recommend maintaining meaningful stock exposure even in retirement.

    Common Asset Allocation Mistakes to Avoid

    These errors are surprisingly common — and surprisingly costly:

    Mistake 1: Setting It and Forgetting It Without Rebalancing

    If you set a 70/30 allocation in 2019 and never rebalanced, the bull market likely pushed you to 85/15 or higher by 2022 — taking on far more risk than you intended, right before a volatile period. Rebalancing isn’t optional maintenance. It’s core to the strategy.

    Mistake 2: Confusing Account-Level Allocation With Total Portfolio Allocation

    Many investors look at each account — their 401(k), their Roth IRA, their taxable brokerage — in isolation. You need to look at your total asset allocation across all accounts. If your 401(k) is 80% stocks and your Roth IRA is also 80% stocks, you’re not as diversified as you think even if the accounts look different on paper.

    Mistake 3: Letting Fear or Greed Override Your Written Plan

    Selling stocks during a market crash and "waiting for things to stabilize" is one of the most expensive moves an investor can make. According to JP Morgan’s annual Guide to the Markets, missing just the 10 best trading days in the S&P 500 over a 20-year period cuts your total return nearly in half. Your written asset allocation plan is your defense against this impulse.

    Mistake 4: Ignoring the Bond Side of the Portfolio

    Many younger investors dismiss bonds entirely as "boring." While aggressive stock allocations make sense for long horizons, having zero bonds means your portfolio could drop 40-50% in a severe bear market with no cushion — potentially forcing you to sell equities at the worst time if you need cash.

    Mistake 5: Not Adjusting Allocation as You Age

    Your risk tolerance and time horizon change over time. A 60% stock allocation at 35 is quite aggressive; at 62 with retirement three years away, it may be dangerously so. Most financial planners recommend gradually shifting toward a more conservative allocation in the 10-15 years before retirement. Target-date funds do this automatically, which is part of their appeal for hands-off investors.

    Alternatives to Consider

    Asset allocation is a strategy, not a single product. Here are a few ways to implement it depending on your situation:

    Target-Date Funds

    Pros: Automatic, hands-off, built-in diversification and rebalancing. Glide path automatically becomes more conservative as you approach retirement. Low cost at major providers like Vanguard and Fidelity (expense ratios often 0.10-0.15%).
    Cons: One-size-fits-all — doesn’t account for your specific risk tolerance, pension income, or other assets. Less tax-efficient in taxable accounts.

    Best for: Investors who want set-it-and-forget-it simplicity, especially inside 401(k) accounts.

    Robo-Advisors

    Pros: Personalized risk questionnaire, automatic rebalancing, tax-loss harvesting (at many providers), low minimum investments. Annual fees typically 0.25-0.50%.
    Cons: Less flexibility than self-directed investing. Fee adds up over time on large portfolios.

    Best for: Investors who want automation with a bit more personalization than target-date funds offer.

    DIY Three-Fund Portfolio

    Pros: Maximum simplicity and low cost. A classic three-fund portfolio (U.S. total market index, international index, U.S. bond index) gives you broad diversification in just three holdings.
    Cons: Requires you to manually rebalance and adjust allocation over time.

    Best for: Cost-conscious, disciplined investors comfortable with a hands-on approach.

    If you’re also thinking about how to grow wealth outside of your investment portfolio, you might explore Bond Ladder Strategy: How to Build Steady Income as a complementary income approach.

    Frequently Asked Questions

    What is the best asset allocation for someone in their 40s?

    There’s no single "best" answer, but a common starting point for a 40-year-old with a 25-year retirement horizon is a 70/30 or 80/20 stock-to-bond split. Your specific income stability, pension benefits, risk tolerance, and other savings will all affect the right mix. Generally speaking, you still have enough time horizon to absorb stock market volatility while beginning to add some bond exposure for balance.

    How often should I rebalance my portfolio?

    Most financial planners recommend rebalancing annually or whenever an asset class drifts more than 5 percentage points from its target. Rebalancing more frequently than quarterly rarely adds value and can increase transaction costs and tax events in taxable accounts.

    Can I use asset allocation inside my 401(k)?

    Absolutely — and your 401(k) is often the best place to start because you can rebalance without triggering taxable events. Most 401(k) platforms offer automatic rebalancing options and a range of index funds across different asset classes. Review your fund lineup and build your target allocation using the lowest-cost options available.

    What happens to my asset allocation when I retire?

    In retirement, the general principle is to shift toward a more conservative allocation to protect against sequence-of-returns risk — the danger that a market crash early in retirement, combined with portfolio withdrawals, could permanently impair your savings. Many financial planners use the "bucket strategy," keeping 1-2 years of expenses in cash, 3-7 years in bonds, and the remainder in stocks for long-term growth.

    Is a 60/40 portfolio still relevant today?

    The 60/40 portfolio (60% stocks, 40% bonds) came under scrutiny in 2022 when both stocks and bonds fell simultaneously — an unusual correlation event. However, over longer periods, bonds still provide meaningful portfolio diversification. Many advisors now suggest variations like 60/30/10 (adding 10% alternatives such as REITs or commodities) to enhance diversification. The core principle of multi-asset diversification remains as relevant as ever.

    Building Wealth Starts With Getting the Foundation Right

    Asset allocation isn’t the exciting part of investing. It won’t generate dinner party conversation. But it is, according to decades of academic research and real-world data, the most important investment decision you’ll make.

    Start by defining your time horizon and honestly assessing your risk tolerance. Choose an allocation model that reflects your actual situation — not just your best-case scenario. Implement it with low-cost index funds or ETFs. Rebalance annually. And adjust gradually as you age.

    That’s the entire framework. Its power comes from consistency and discipline, not complexity.

    If you’re also building out your broader financial plan, consider reviewing Dollar-Cost Averaging: The Smart Way to Invest Consistently — a strategy that pairs naturally with a sound asset allocation plan.

    This article is for educational purposes only and does not constitute financial, tax, or investment advice. Always consult a licensed financial advisor, CPA, or attorney before making financial decisions.
  • Bond Ladder Strategy: How to Build Steady Income

    Bond Ladder Strategy: How to Build Steady Income

    Bond Ladder Strategy: How to Build Steady Income

    Learn how a bond ladder can generate predictable cash flow and reduce interest rate risk — a strategy used by thousands of retirees and conservative investors across the US.

    Introduction

    According to the Federal Reserve’s 2025 Survey of Consumer Finances, nearly 45% of Americans within a decade of retirement have little to no fixed-income allocation in their portfolios. That’s a significant gap — especially when stock market volatility can wipe out years of gains right when you need stability most.

    If you’re a working professional or small business owner between 40 and 65, you’ve probably asked yourself: How do I generate reliable income without betting everything on the stock market? The bond ladder strategy is one of the most time-tested answers to that question.

    In this guide, you’ll learn exactly what a bond ladder is, how it works in practical terms, what it costs to build one, and the most common mistakes investors make when setting one up. By the end, you’ll know whether this approach fits your financial situation — and how to get started.

    What Is a Bond Ladder and How Does It Work?

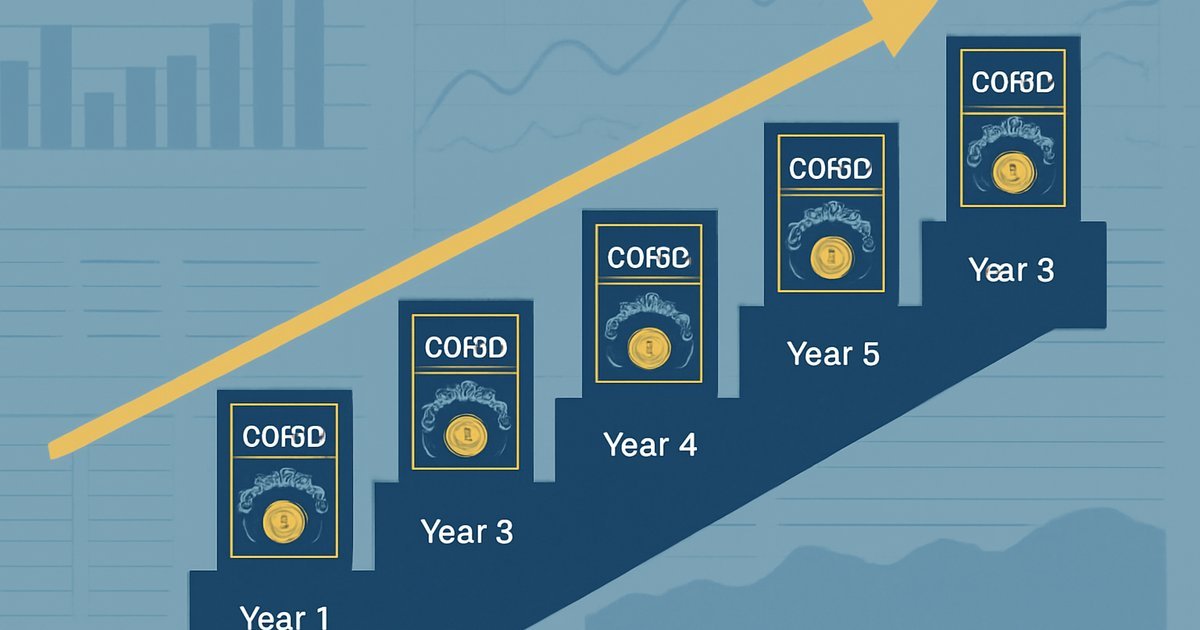
    A bond ladder is an investment strategy where you purchase multiple bonds with staggered maturity dates — for example, bonds maturing in 1 year, 2 years, 3 years, 4 years, and 5 years. As each bond matures, you either spend the proceeds (if you need income) or reinvest them into a new long-term bond at the end of the ladder.

    Think of it like rungs on a ladder. Each rung represents a bond at a different maturity. You’re never fully locked into one interest rate environment, and you always have bonds coming due at regular intervals.

    Who does this apply to? Generally speaking, bond ladders are most useful for:

    • Pre-retirees and retirees who need predictable income
    • Conservative investors uncomfortable with heavy stock market exposure
    • Small business owners who need to park reserves safely
    • Anyone with a specific future cash need (tuition, a home purchase, or a business investment)

    Bonds themselves are essentially loans you make to a government or corporation. In return, the issuer pays you interest — called a coupon — at regular intervals and returns your principal at maturity. The US bond market is the largest in the world, with over $50 trillion in outstanding debt, according to data from the Securities Industry and Financial Markets Association (SIFMA).

    Key Benefits of a Bond Ladder

    The bond ladder strategy offers several concrete advantages over simply buying a single bond or a bond mutual fund — and understanding those differences matters when you’re protecting decades of savings.

    1. Reduces Interest Rate Risk

    When interest rates rise, bond prices fall. If you own a single long-term bond and rates spike, your investment loses value — at least on paper. With a ladder, only a portion of your holdings is exposed to any single rate environment. As shorter-term bonds mature, you reinvest at higher prevailing rates, which actually benefits you over time.

    2. Provides Predictable Cash Flow

    Every rung of your ladder produces income on a known schedule. For retirees, this can replace or supplement Social Security income with guaranteed payouts. According to Vanguard’s fixed-income research, investors who ladder Treasury bonds can generate consistent income streams over 5 to 20 years without relying on fund manager decisions.

    3. Eliminates Fund Manager Risk

    Unlike bond mutual funds, individual bonds in a ladder have a defined maturity date. You get your principal back — period. Bond funds, by contrast, can and do lose value with no guaranteed recovery timeline.

    4. Liquidity at Regular Intervals

    With bonds maturing regularly, you always have access to cash without being forced to sell at a loss. In most cases, this predictability makes financial planning far more manageable — especially in retirement.

    For example, consider Sarah, 58, a former marketing director. She built a $200,000 bond ladder using US Treasuries spread across five years. Every 12 months, $40,000 matures — giving her a reliable cash cushion while her 401(k) stays invested in stocks for growth.

    How to Build a Bond Ladder: Step-by-Step

    Building a bond ladder is more straightforward than most investors expect. Here’s how to do it in plain terms.

    1. Determine your total investment amount. Bond ladders generally work best with at least $50,000 to $100,000, though some platforms allow you to start smaller. Decide how much you want to allocate to fixed income based on your overall asset allocation.
    2. Choose your bond types. You have several options:
      • US Treasury bonds — backed by the full faith and credit of the US government, essentially zero default risk
      • Municipal bonds (munis) — often tax-exempt at the federal level, great for high earners in higher brackets
      • Corporate bonds — higher yields but more risk; investment-grade corporate bonds (rated BBB or higher by S&P) are most common in ladders
      • FDIC-insured CDs (Certificates of Deposit) — a simpler ladder alternative for smaller amounts
    3. Select your time horizon and rung intervals. A typical ladder spans 5 to 10 years with annual maturities. A 5-year ladder might have bonds maturing in 2026, 2027, 2028, 2029, and 2030.
    4. Purchase bonds through a brokerage. Fidelity, Vanguard, Charles Schwab, and TD Ameritrade all offer bond screeners and secondary market access. You can also buy Treasury bonds directly at TreasuryDirect.gov with no fees.
    5. Decide on a reinvestment rule. When a bond matures, will you reinvest at the long end of the ladder or spend the proceeds? Define this in advance so emotions don’t drive the decision during market volatility.
    6. Track coupon payment schedules. Many investors stagger bonds so that coupon payments arrive monthly or quarterly, providing a more consistent income stream rather than semi-annual lump sums.

    If you’re also focused on consistent accumulation strategies, pairing a bond ladder with a dollar-cost averaging approach for your equity allocation can provide a strong balance between growth and stability.

    Costs, Fees, and Risks to Understand

    No strategy is without drawbacks. In most cases, a bond ladder is a low-cost approach — but there are real costs and risks to account for before you commit.

    Transaction Costs and Markups

    When buying bonds on the secondary market through a broker, you often pay a markup — the difference between what the dealer paid and what you pay. These markups can range from 0.5% to 2% of the bond’s face value, according to FINRA data. Always compare prices across brokers or use TreasuryDirect for new Treasury issues to avoid markups entirely.

    Inflation Risk

    If inflation rises significantly, fixed coupon payments lose purchasing power. One solution: include Treasury Inflation-Protected Securities (TIPS) in your ladder. TIPS adjust their principal value with the Consumer Price Index (CPI), providing some inflation protection.

    Default Risk

    Corporate bonds carry default risk — the issuer might not be able to repay you. Sticking to investment-grade bonds (rated BBB- or above) and limiting corporate bonds to no more than 30–40% of your ladder significantly reduces this risk.

    Liquidity Risk

    If you need to sell a bond before it matures, you may get less than face value — particularly if interest rates have risen since you bought it. This is why matching your bond maturities to your actual cash needs is critical.

    Tax Implications

    Interest income from Treasury bonds is subject to federal income tax but exempt from state and local taxes. Municipal bond interest is typically exempt from federal tax. Corporate bond interest is fully taxable. Depending on your tax bracket, the after-tax yield of a muni bond may exceed a higher-yielding corporate bond. Always run the numbers or consult a CPA.

    This is for educational purposes — consult a licensed financial advisor for personalized guidance specific to your tax situation and income level.

    Common Mistakes to Avoid

    Even a well-designed bond ladder can underperform or cause headaches if you make these common errors.

    Mistake 1: Ignoring Credit Quality

    Chasing yield by buying low-rated bonds (BB or below — so-called "junk bonds") can work in certain economic conditions, but it introduces significant default risk into what’s supposed to be a stable strategy. In most cases, a bond ladder should be anchored in investment-grade securities.

    Mistake 2: Not Matching Maturities to Cash Needs

    If you build a 10-year ladder but need significant cash in year 3 for a home purchase or medical expense, you may be forced to sell bonds at a loss. Before building your ladder, map out your expected financial needs for each year of the ladder’s duration.

    Mistake 3: Over-concentrating in One Issuer

    Some investors buy multiple bonds from the same corporation to get consistent higher yields. If that company faces financial trouble, multiple rungs of your ladder could be at risk simultaneously. Diversify across issuers and sectors.

    Mistake 4: Forgetting to Reinvest Strategically

    When a bond matures, many investors simply let the cash sit in a money market account indefinitely. This defeats the purpose of the ladder. Set a reminder or automatic reinvestment rule to keep the strategy working for you.

    Mistake 5: Underestimating Inflation’s Erosion

    A 4% yield sounds solid — until inflation runs at 5%. Over a 10-year ladder, this gap can meaningfully reduce your real purchasing power. Consider mixing in TIPS or I-Bonds (US Savings Bonds with inflation adjustments) to hedge this risk.

    Alternatives to Consider

    A bond ladder isn’t the only way to generate fixed income. Depending on your situation, one of these alternatives might suit you better — or work alongside a ladder.

    1. Bond Mutual Funds or ETFs

    Pros: Instant diversification, easy to manage, low minimums, highly liquid.
    Cons: No guaranteed maturity date or principal return; fund value fluctuates daily; less control over individual holdings.
    Best for: Beginners or those with smaller portfolios who want broad fixed-income exposure without managing individual bonds. For more on ETFs, you can explore real estate income investing as a complementary strategy.

    2. High-Yield Savings Accounts and CDs

    Pros: FDIC-insured up to $250,000 per depositor, simple to set up, predictable returns.
    Cons: Yields are typically lower than bonds, especially for longer-term CDs; interest is fully taxable.
    Best for: Investors who want a simpler version of the ladder concept with lower minimums and no broker required.

    3. Annuities (Fixed or Fixed-Indexed)

    Pros: Can guarantee income for life, useful for longevity planning in retirement.
    Cons: Complex product structures, high surrender charges, and often significant insurance company fees. Generally speaking, these products require careful evaluation by a licensed advisor before purchase.
    Best for: Retirees who want income they literally cannot outlive and who have already maxed out other retirement vehicles.

    Frequently Asked Questions

    How much money do I need to start a bond ladder?

    You can start with as little as $1,000 using CDs or I-Bonds from TreasuryDirect.gov, but a traditional Treasury or corporate bond ladder typically requires $50,000 to $100,000 to build meaningful diversification across maturities. For smaller amounts, a short-term bond ETF may be more practical.

    Are bond ladders good for retirement income?

    Yes — in most cases, bond ladders are an excellent complement to Social Security and 401(k) withdrawals in retirement. They provide predictable cash flow and eliminate the risk of being forced to sell stocks during market downturns to cover expenses.

    What’s the best type of bond for a ladder?

    US Treasury bonds and TIPS are the most common choices because they carry no default risk. For investors in higher tax brackets (32% or above), municipal bonds may offer better after-tax yields. Corporate bonds can boost returns but add risk — stick to investment-grade if you include them.

    What happens if interest rates rise after I build my ladder?

    Rising rates will reduce the market value of your existing bonds, but this doesn’t matter if you hold them to maturity — you’ll still receive your full principal back. Meanwhile, as shorter-term bonds mature, you reinvest at higher rates, which actually benefits you over time.

    Can I build a bond ladder inside a Roth IRA or 401(k)?

    Yes. Building a bond ladder inside a tax-advantaged account like a Roth IRA or traditional IRA shields coupon payments from annual taxation — a significant benefit, especially for corporate bonds. However, IRS contribution limits apply to these accounts, and you’d be using funds already inside the account to purchase the bonds.

    Conclusion

    A bond ladder is one of the most disciplined, transparent, and time-tested strategies for generating reliable income from your portfolio. It doesn’t promise outsized returns — and that’s exactly the point. It gives you predictability, protection from interest rate swings, and flexibility when life gets expensive.

    If you’re within 10 to 15 years of retirement or simply need a portion of your portfolio to behave with more certainty, building even a modest ladder of US Treasuries is a concrete first step worth taking. Start by mapping out your cash needs over the next five years, then explore TreasuryDirect.gov or a major brokerage’s bond screener to price out your first rungs.

    As always, your specific tax bracket, income needs, and overall financial picture will shape how a bond ladder should look for you. Working with a licensed financial advisor or CPA is the best way to tailor this strategy to your situation.

    Financial Disclaimer: This article is for educational purposes only and does not constitute financial, tax, or investment advice. Always consult a licensed financial advisor, CPA, or attorney before making financial decisions.

  • Dollar-Cost Averaging: The Smart Way to Invest Consistently

    Dollar-Cost Averaging: The Smart Way to Invest Consistently

    What Is Dollar-Cost Averaging and How Does It Work?

    Dollar-cost averaging (DCA) is an investment strategy where you invest a fixed dollar amount at regular intervals — weekly, biweekly, or monthly — regardless of what the market is doing. Instead of trying to time the market perfectly, you buy consistently over time.

    Here’s how it plays out in practice: suppose you invest $300 every month into an S&P 500 index fund. Some months, the fund is up and your $300 buys fewer shares. Other months, the market dips and your $300 stretches further, buying more shares at a lower price. Over time, your average cost per share tends to smooth out — reducing the risk of making one large investment right before a downturn.

    This strategy applies to virtually any investor who contributes regularly to a 401(k), Roth IRA, or taxable brokerage account. If you’ve ever had money automatically deducted from your paycheck into a retirement plan, you’ve already been using dollar-cost averaging — you just may not have known it by name.

    The core idea is simple: consistency beats timing. According to research from Vanguard, trying to time the market successfully over long periods is extremely difficult even for professional investors, making DCA a practical and psychologically sound alternative for most working Americans.

    Key Benefits of Dollar-Cost Averaging

    According to a 2024 Gallup survey, nearly 61% of Americans report owning stock — but a far smaller percentage invest with any kind of systematic strategy. Dollar-cost averaging offers several concrete advantages that make it especially well-suited for the average investor.

    1. Reduces Emotional Decision-Making

    Market volatility triggers fear. When the S&P 500 dropped roughly 25% in 2022, many investors panic-sold at a loss. DCA removes the emotional element by automating your investment schedule. You invest the same amount on the same date, no matter what the headlines say.

    2. Lowers Your Average Cost Per Share

    Because you buy more shares when prices are low and fewer when prices are high, your average cost per share can end up lower than if you had invested a lump sum at a single, potentially unfavorable price point. This is the mathematical core of the strategy.

    3. Accessible on Any Budget

    You don’t need $50,000 to get started. Many brokerage platforms — including Fidelity and Charles Schwab — now offer fractional shares and zero-minimum accounts, meaning you can start DCA with as little as $25 or $50 a month. This democratizes investing for people who are still building their income.

    4. Builds Long-Term Wealth Through Compounding

    When you invest $300 a month at an average annual return of 7% (a historically reasonable long-term estimate for diversified stock portfolios, though not guaranteed), you’d have approximately $180,000 after 25 years. The combination of regular contributions and compounding interest is a powerful wealth-building engine over time.

    5. Works in Up and Down Markets

    Unlike lump-sum investing, which is most effective when markets are trending upward immediately after your investment, DCA performs well across different market environments. It doesn’t require you to predict market direction — which is something very few investors do successfully.

    How to Get Started with Dollar-Cost Averaging: Step-by-Step

    Setting up a DCA strategy is straightforward. Here’s a practical roadmap tailored for U.S. investors in their 30s through 60s.

    1. Define your monthly investment amount. Start with what you can afford to invest consistently without disrupting your budget. Even $100 a month is a meaningful start. The key is sustainability — choose an amount you won’t need to stop contributing during a tough month.
    2. Choose an account type. If you have access to a 401(k) through your employer, maximize that first — especially if your employer matches contributions (that’s an immediate 50–100% return on part of your investment). Next, consider a Roth IRA (2026 contribution limit: $7,000, or $8,000 if you’re 50 or older). For additional investing beyond tax-advantaged accounts, a taxable brokerage account works well.
    3. Select your investment vehicle. For most DCA investors, low-cost index funds or ETFs that track broad market indices — like the S&P 500 or total stock market — are the most efficient vehicles. They offer instant diversification and typically have expense ratios under 0.10%.
    4. Set up automatic contributions. Log in to your brokerage or retirement plan and schedule recurring automatic transfers on your preferred date. Automating removes the willpower element entirely — you never have to decide whether to invest each month.
    5. Stay the course during downturns. This is where most DCA investors struggle. When the market drops 15%, resist the urge to pause contributions. A market dip is actually an opportunity — your fixed dollar amount buys more shares at lower prices. Historically, U.S. markets have recovered from every downturn, though past performance does not guarantee future results.
    6. Review annually, not daily. Check your portfolio allocation once or twice a year to ensure it still aligns with your risk tolerance and timeline. Rebalance if one asset class has grown significantly out of proportion. But avoid checking your balance every day — it leads to emotional decisions.

    Costs, Fees, and Risks You Should Know

    Dollar-cost averaging is low-cost by design, but there are still real risks and expenses to factor in before you commit.

    Transaction Fees

    Most major U.S. brokerages — Fidelity, Schwab, Vanguard, and others — now offer commission-free stock and ETF trades. However, some mutual funds may still carry transaction fees or sales loads. Always verify the fee structure before selecting your investment vehicle.

    Expense Ratios

    Even a small difference in fund fees compounds significantly over time. A fund with a 1% expense ratio costs you 10 times more annually than one with 0.10%. Over 30 years, that difference can add up to tens of thousands of dollars in lost returns. Always compare expense ratios before investing.

    Tax Implications in Taxable Accounts

    In a taxable brokerage account, each purchase creates a separate tax lot. When you eventually sell, the IRS requires you to track your cost basis for each purchase. This can become administratively complex over time. Tax-advantaged accounts like 401(k)s and IRAs avoid this issue since gains aren’t taxed until withdrawal (or not at all, in the case of Roth accounts).

    Market Risk Still Exists

    DCA does not eliminate market risk. If you invest regularly into a declining asset class over a long period and that asset never recovers, you will still lose money. Diversification across asset classes — stocks, bonds, and potentially real estate via REITs — helps manage this risk, but no strategy is entirely risk-free.

    Opportunity Cost vs. Lump-Sum Investing

    Research from Vanguard found that lump-sum investing outperforms DCA approximately two-thirds of the time in rising markets. This makes sense mathematically — money invested earlier has more time to compound. However, DCA remains the superior choice for investors who don’t have a large lump sum available, or who would otherwise let fear keep them on the sidelines entirely.

    Common Dollar-Cost Averaging Mistakes to Avoid

    Even a straightforward strategy like DCA can go wrong when investors make predictable errors. Here are the most costly ones to watch out for.

    Mistake 1: Stopping Contributions During Market Crashes

    The most damaging thing you can do to a DCA strategy is pause your contributions exactly when the market drops. This eliminates the core advantage of the strategy — buying more shares at lower prices. In March 2020, when the market fell roughly 34% in weeks, investors who stopped their DCA contributions missed one of the most powerful recovery rallies in U.S. market history. Stay the course.

    Mistake 2: Choosing High-Fee Funds

    Investing $300 a month consistently for 30 years is impressive. But if you’re doing it inside a mutual fund with a 1.5% annual expense ratio instead of a 0.03% index fund, the fee difference alone could cost you upward of $100,000 over your investing lifetime. Always check the expense ratio before hitting "buy."

    Mistake 3: Not Taking Advantage of Tax-Advantaged Accounts First

    Many investors open a standard taxable brokerage account before maximizing their 401(k) match or Roth IRA. That’s leaving free money and tax benefits on the table. In 2026, you can contribute up to $23,500 to a 401(k) (or $31,000 if you’re 50 or older). Prioritize these accounts before investing in taxable accounts. For more on maximizing retirement accounts, our guide on Roth IRA conversion strategy is a useful starting point.

    Mistake 4: Investing in a Single Stock Instead of Diversified Funds

    DCA works best when applied to diversified, broad-market investments. Applying it to a single company’s stock concentrates your risk significantly — if that company underperforms or goes bankrupt, your entire DCA portfolio suffers. Stick to diversified index funds or ETFs as your primary DCA vehicle.

    Mistake 5: Ignoring Inflation on Fixed Contribution Amounts

    If you set a $200/month contribution in 2015 and never adjusted it, you’re effectively investing less in real terms by 2026 due to inflation. As your income grows, revisit your contribution amount annually and increase it proportionally. Even a $25 or $50 monthly increase each year compounds into significantly higher returns over time.

    Alternatives to Dollar-Cost Averaging

    DCA is not the only way to invest systematically. Depending on your financial situation, one of these alternatives may be a better fit — or a useful complement.

    1. Lump-Sum Investing

    Best for: Investors who receive a windfall (inheritance, bonus, or 401(k) rollover) and have a long time horizon.
    Pros: Historically outperforms DCA in rising markets; maximizes time in the market.
    Cons: Requires strong emotional discipline during immediate volatility; poor timing can result in short-term paper losses. If you’re considering a large rollover, review how it fits with your broader financial plan before acting.

    2. Value Averaging

    Best for: More sophisticated investors who want to be more aggressive during downturns.
    Pros: Adjusts your contributions based on portfolio performance — you invest more when the market drops and less when it rises, potentially outperforming standard DCA.
    Cons: Requires more active management, discipline, and liquidity. You may need to contribute substantially more during downturns than your budget allows.

    3. Target-Date Funds with Automatic Contributions

    Best for: Investors who want a completely hands-off approach, especially within a 401(k).
    Pros: Automatically adjusts asset allocation as you approach retirement; built-in diversification.
    Cons: Typically carry slightly higher expense ratios than individual index funds; less flexibility in asset allocation control. Still, for many investors — particularly those who find investing overwhelming — these funds combined with automatic contributions represent an effective DCA approach by default.

    Frequently Asked Questions About Dollar-Cost Averaging

    Is dollar-cost averaging better than lump-sum investing?

    It depends on your situation. Research from Vanguard shows lump-sum investing outperforms DCA about two-thirds of the time in historically rising markets. However, DCA is the better choice if you don’t have a large lump sum, if you’re investing monthly from your paycheck, or if market volatility would cause you to panic-sell after a large one-time investment. The best strategy is one you’ll actually stick to.

    What is a good amount to start with for DCA?

    There’s no universal right answer, but $100 to $500 per month is a realistic range for most working professionals. What matters more than the dollar amount is consistency. Start with what you can sustain without financial stress, then increase the amount as your income grows. Many brokerage platforms allow automatic investments with no minimum.

    Can I use DCA inside a Roth IRA?

    Absolutely — and it’s one of the most tax-efficient ways to apply DCA. You contribute after-tax dollars, your investments grow tax-free, and qualified withdrawals in retirement are also tax-free. The 2026 Roth IRA contribution limit is $7,000 (or $8,000 if you’re 50 or older), subject to income limits set by the IRS.

    Does dollar-cost averaging work in a bear market?

    Yes — and it arguably works best in bear markets. When asset prices fall, your fixed monthly contribution buys more shares. If the market eventually recovers (as U.S. markets have historically done over long periods), those extra shares purchased at lower prices contribute significantly to your long-term gains. The critical requirement is that you must continue investing during the downturn rather than stopping out of fear.

    How do I track my average cost per share with DCA?

    Most brokerage platforms automatically track your average cost basis across all purchases. You can view this in your account’s portfolio section. For tax purposes in taxable accounts, you can also choose a cost-basis accounting method — such as FIFO (first in, first out) or specific identification — which your broker will apply when you sell shares. Consult a CPA if you’re unsure which method is most tax-efficient for your situation.

    Final Takeaways: Is Dollar-Cost Averaging Right for You?

    Dollar-cost averaging won’t make you rich overnight, and it doesn’t eliminate market risk. What it does is give you a disciplined, accessible, and emotionally sustainable framework for building wealth over time — one that works whether you’re just starting out in your 30s or adding to an established portfolio in your 50s and 60s.

    The most powerful thing about DCA isn’t the math — it’s the habit. Investors who contribute consistently, avoid panic-selling, and keep their fees low tend to build significantly more wealth over time than those who try to outsmart the market with perfect timing.

    If you’re already contributing to a 401(k) or Roth IRA, you’re already doing it. If you’re not, today is a reasonable time to start — whether that means opening a brokerage account, setting up automatic contributions, or simply increasing what you’re already putting in each month.

    Take one concrete next step this week: calculate what you can comfortably invest each month, open or log in to your investment account, and set up an automatic recurring contribution. Small, consistent actions compound into meaningful financial outcomes over time.

    This article is for educational purposes only and does not constitute financial, tax, or investment advice. Always consult a licensed financial advisor, CPA, or attorney before making financial decisions.